Concrete Pumping insurance
Concrete pumping insurance built around your operation.
Your pump is a vehicle on the road, working equipment on the jobsite, and the reason the pour can happen. We help you put the coverage and support around all three.
For boom pump, line pump, and concrete placing operations.
Your team
A direct line to your risk advisors.
ACPA member
Part of the concrete pumping industry.
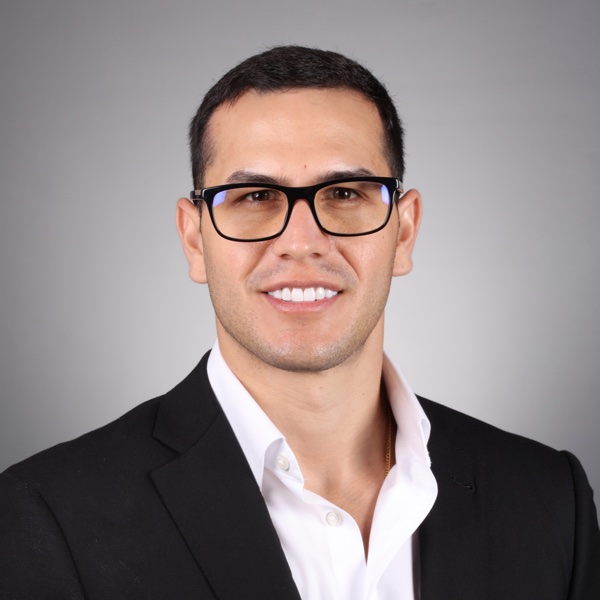
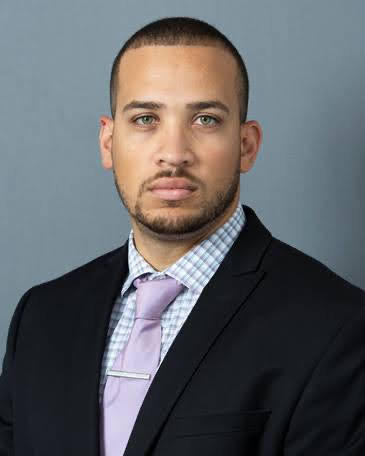
Arvor is a member of the American Concrete Pumping Association (ACPA), and we are active participants in the industry. Simon Mejia and Carlos Hidalgo lead our concrete pumping practice, with a focus on the equipment, contracts, and day-to-day risks that shape your business.
That starts with understanding your operation: what you pump, where you work, how your fleet is maintained, and what your customers require before you arrive.
Arvor in the ACPA member announcementHow we help
Coverage that follows the pump from the road to the pour.
We review how the policies fit together, including the equipment you own, the work you take on, and the obligations in your contracts.
Pump trucks and equipment
Coordinate commercial auto and equipment coverage for boom pumps, line pumps, trailer-mounted line pumps, skid-mounted line pumps, pump trucks, hoses, and related equipment. Check values, deductibles, and the treatment of rented equipment before a loss.
Jobsite liability
Review general liability and excess limits against the work you perform and the contracts you sign. Pay attention to exclusions, additional insured requirements, and the transition from driving to pumping.
Your people
Align workers’ compensation with your crews and operations. Bring training, safety practices, and claims history into the insurance conversation so the program reflects how you actually work.
Contracts, certificates, and claims
Work through insurance requirements before the job starts, coordinate certificates and endorsements, and help manage the insurance response when an incident interrupts a pour.
Where we start
Start with your fleet, your work, and your current coverage.
Tell Simon or Carlos about your pumps, the projects you take on, and what is getting difficult with your current insurance. We can review your policies, equipment schedule, claims history, and a sample customer contract to identify the questions that need attention.
Choose your advisorCommon questions
Concrete pumping insurance, explained.
What insurance does a concrete pumping company need?
A concrete pumping company typically reviews commercial auto, general liability, contractors equipment or inland marine, workers’ compensation, and umbrella or excess liability. The right combination depends on the equipment, operations, contracts, and policy terms.
Does commercial auto insurance cover the pump while it is operating?
Do not assume a commercial auto policy covers every pumping exposure. The truck, the attached equipment, and liability during pumping can involve different policies. We review how your auto, equipment, and liability coverage fit together.
Can Arvor help with certificates and contractor insurance requirements?
Yes. We help review customer insurance requirements and coordinate certificates and endorsements with the insurance program. A certificate provides evidence of coverage; it does not change the policy or add coverage on its own.
Is Arvor a member of the ACPA?
Yes. Arvor is a member of the American Concrete Pumping Association and an active industry participant. Simon Mejia and Carlos Hidalgo are the risk advisors responsible for our concrete pumping practice.
Who should I contact about concrete pumping insurance?
Contact Simon Mejia at s.mejia@arvorinsurance.com or Carlos Hidalgo at c.hidalgo@arvorinsurance.com. They lead Arvor’s concrete pumping practice and can discuss your operation and current insurance.
Let’s talk about your business.
Connect with Simon Mejia or Carlos Hidalgo to discuss your current coverage and what you need from your broker.
Coverage and services depend on your operations, agreed scope, insurer underwriting, and policy terms. See our coverage disclosures.